
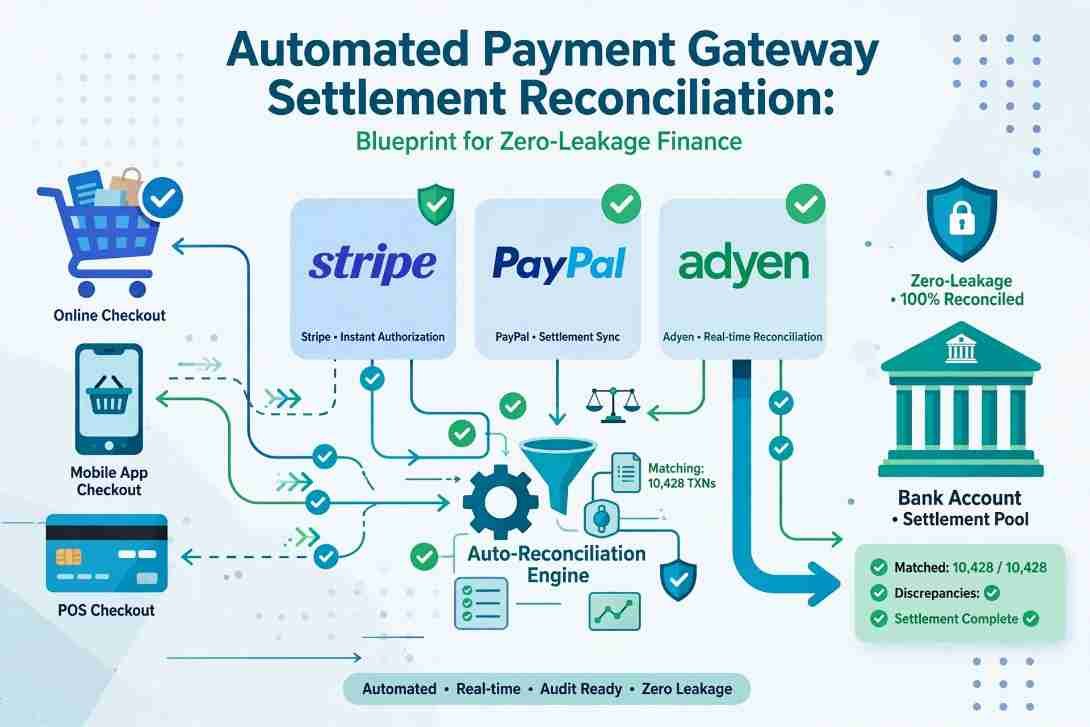
Last quarter, a mid-market e-commerce client asked me to audit why their cash balance lagged behind reported sales by $42,000. Two days of spreadsheet forensics revealed a classic failure: unlogged gateway chargebacks, silent fee hikes, and batch deposits stuck in transit. Implementing automated payment gateway settlement reconciliation fixed that blind spot in less than a week.
When you process thousands of daily checkouts, a customer payment almost never matches your bank deposit one-to-one. Modern finance teams need a programmatic bridge connecting order logs, processor payouts, and bank feeds without human intervention.
Why Manual Payment Matching Breaks Down at Scale
Cross-referencing CSV exports in Excel works when you process fifty orders a week. Once daily volume crosses a few hundred transactions, manual matching becomes an expensive liability that hides revenue leakage.
The Gross-to-Net Deduction Trap

Payment processors rarely transfer the exact gross dollar amount a customer pays at checkout. Instead, gateways remit net lump sums after stripping out Merchant Discount Rates (MDR), per-transaction fixed fees, applicable taxes, refunds, and dispute chargebacks.
If a customer buys a $100 item, your bank might receive $96.80 two days later. Without software parsing those line-item deductions, your accounting team wastes hours hunting for $3.20 variances across thousands of rows.
Timing Delays and Multi-Processor Fragmentation
Bank clearing cycles introduce unavoidable timing gaps. Most US processors operate on T+1 or T+2 schedules via standard NACHA ACH clearing windows, meaning Friday’s sales hit your checking account on Tuesday.
Scaling merchants compound this headache by running multiple processors simultaneously—such as Stripe for cards, PayPal for wallets, and Adyen for international buyers. Each platform exports settlement reports with wildly different column headers, timestamps, and fee structures. If you sell globally, managing foreign exchange spreads alongside your multi-currency accounting rules turns manual reconciliation into a full-time bottleneck.
How Automated Payment Gateway Settlement Reconciliation Works
A reliable reconciliation engine eliminates spreadsheet gymnastics by running a continuous, rule-based pipeline. Over the past five years of building financial data workflows, I have found that every high-performing setup relies on three core phases.
Data Ingestion and Schema Normalization
First, the engine pulls raw transaction logs from your Order Management System (OMS), settlement reports from gateway APIs, and cleared credit entries from corporate bank feeds (via MT940, CAMT.053, or open banking APIs).
Because gateways label identifiers inconsistently, the pipeline immediately normalizes every record into a uniform schema. Dates convert to UTC, currencies standardize to ISO codes, and processor-specific IDs map to a single internal reference key. Connecting this ingestion layer directly into your broader quote-to-cash integration architecture ensures downstream ERPs receive clean, standardized events from day one.
The Three-Stage Matching Funnel

True reconciliation requires three-way verification: tying internal orders to gateway captures, and then grouping settled captures to match lump-sum bank credits. I structure this logic as a strict three-stage funnel:
- Order-to-Gateway Match (1:1): The system pairs internal OMS orders against gateway capture logs using the unique payment ID. Captures missing from your OMS get flagged immediately as orphan transactions—usually caused by dropped checkout webhooks.
- Contracted Fee Audit (Row-Level): Before looking at bank statements, the engine recalculates expected fees for every single transaction against your contracted rate card. If your processor quotes 2.9% + $0.30 per Stripe payout documentation or your custom merchant agreement, the software verifies that the deducted fee matches to the exact cent.
- Gateway Batch-to-Bank Match (Many:1): Payment gateways bundle hundreds of individual captures and negative refund adjustments into a single payout identified by a Unique Transaction Reference (UTR) or trace number. The software sums the net settled amounts per batch and matches that total against the exact credit line on your bank statement.
Automated Fee Audits and Exception Routing
When every check passes, the system posts balanced journal entries—debiting cash and merchant fee expenses while crediting accounts receivable—directly into NetSuite, QuickBooks, or SAP. Maintaining clean, itemized fee records also keeps your books compliant with IRS business recordkeeping standards during tax season.
When a check fails, the engine isolates only the broken records. Finance analysts never touch the 99.4% of clean transactions; they only review flagged exceptions like short-credited batches, duplicate refunds, or overcharged interchange rates.
Designing a Database Schema for Three-Way Reconciliation

If you plan to build a custom reconciliation microservice rather than buying off-the-shelf software, your database design will make or break accuracy. Never store monetary values as floating-point numbers (FLOAT or DOUBLE), which introduce silent rounding drift across millions of rows. Always store amounts as BIGINT integers representing cents.
| Table Name | Primary Purpose | Key Columns to Include |
| internal_orders | Source of truth from OMS/ERP | order_id (PK), gateway_payment_id (Indexed), gross_cents, status |
| gateway_transactions | Normalized settlement line items | gateway_txn_id (PK), order_id, txn_type, gross_cents, fee_cents, net_cents, utr_trace_id |
| bank_statement_entries | Parsed corporate bank credits | bank_entry_id (PK), value_date, credit_cents, raw_narration, parsed_utr |
| reconciliation_ledger | Audit trail and exception state | recon_id (PK), order_id (FK), gateway_txn_id (FK), bank_entry_id (FK), fee_variance_cents, recon_status |
This relational structure cleanly solves the cardinal mismatch between individual customer checkouts and aggregated bank deposits. By indexing utr_trace_id across both gateway_transactions and bank_statement_entries, a single SQL GROUP BY query verifies whether an entire day’s settlement landed in your account intact.
Choosing the Right Reconciliation Architecture for Your Stack
Not every company needs to engineer a custom PostgreSQL pipeline from scratch. Your transaction volume and processor count should dictate your tooling choice, aligning with established AICPA internal control best practices.
- Gateway-Native Tools: Best for early-stage businesses using a single processor like Stripe or Adyen. Built-in payout reports handle basic fee breakdowns cleanly, though they lack true bank-statement verification.
- Dedicated Reconciliation Platforms: Ideal for high-volume merchants processing across three or more gateways with complex ERP setups. Tools like HighRadius, BlackLine, or Leapfin provide pre-built bank connectors and deep interchange fee auditing out of the box.
- Custom API Pipelines: Best for tech-forward platforms and marketplaces with proprietary ledger requirements. Building an in-house matching worker using gateway webhooks and bank feeds gives you granular control over split payouts and escrow holds.
Frequently Asked Questions
1. What is automated payment gateway settlement reconciliation?
It is the software-driven process of matching internal order records, gateway payout reports, and bank statements to verify that net collected funds hit your bank account accurately.
2. Why doesn’t my payment gateway payout match my total daily sales?
Gateways deduct processing fees, taxes, refunds, and chargebacks before transferring net funds, and T+1 or T+2 clearing delays shift payouts across calendar dates.
3. How does three-way matching work in payment reconciliation?
Three-way matching verifies that an internal order record matches a gateway capture log, and that the summed net gateway batch matches the exact deposit on your bank statement.
4. When should a business switch from manual to automated payment reconciliation?
You should automate reconciliation once monthly transaction volume exceeds 1,000 orders, you add a second payment processor, or month-end close takes more than two days.
Stop Playing Detective With Your Bank Statements
Your finance team was hired to allocate capital and drive growth, not to play forensic detective across mismatched CSV files every month-end. Leaving settlement verification to manual spreadsheets guarantees that subtle processor fee overcharges and dropped refunds will quietly erode your margins.
Your immediate next step: Pull last month’s settlement summary from your primary payment gateway and compare the total net payouts against actual cleared credits on your bank statement. If you spot even a minor unexplained variance, audit your fee rate card today and start scoping an automated matching workflow before next month’s close.

2 thoughts on “Automated Payment Gateway Settlement Reconciliation: My Blueprint for Zero-Leakage Finance”