A settlement statement can contain dozens of financial entries, yet one incorrect formula can change how much money a client receives or a property buyer must bring to closing. That makes calculation accuracy just as important as processing speed.
Understanding how to automate settlement statement calculations starts with connecting financial records, applying consistent formulas, and building verification checks into every transaction.
For American law firms and real estate professionals, automation can reduce repetitive data entry, simplify complicated disbursements, and produce accurate statements faster. The challenge is choosing a system that understands the financial rules behind each settlement.
Identify the Settlement Type Before Automating
Two industries commonly use settlement statements, but their calculations follow different rules.
Legal and Personal Injury Settlements
Personal injury settlements generally distribute compensation among clients, attorneys, medical providers, lienholders, and other eligible recipients.
A typical calculation begins with the gross settlement and subtracts applicable deductions.
The simplified formula is:
Net Client Recovery = Gross Settlement − Attorney Fees − Case Costs − Approved Liens and Other Deductions
Actual calculations depend on the fee agreement, jurisdiction, lien obligations, and applicable deductions.
Real Estate Closing Statements
Property transactions involve different financial components, including purchase prices, mortgage proceeds, earnest money deposits, title charges, transfer taxes, and property tax adjustments.
The American Land Title Association provides standardized settlement statement forms that help closing professionals organize buyer and seller expenses.
Automated systems should calculate each party’s financial position separately while maintaining balanced transaction records.
How to Automate Settlement Statement Calculations: Six Practical Steps
A dependable workflow combines structured financial data, calculation rules, and document generation.
1. Consolidate Financial Information
Begin by collecting all settlement-related information in a centralized platform. For legal matters, include settlement amounts, contingency agreements, litigation expenses, medical bills, and outstanding liens.
Real estate transactions require purchase agreements, financing terms, title fees, tax obligations, and closing dates. Each financial entry should reference its original document. This prevents employees from relying on inconsistent figures across multiple spreadsheets.
2. Create Standard Calculation Rules

Once records are organized, configure reusable formulas. For example, a law firm processing a $150,000 personal injury settlement might have:
| Settlement component | Amount |
| Gross settlement | $150,000 |
| Attorney fees (33⅓%) | $50,000 |
| Case expenses | $5,000 |
| Approved medical liens | $20,000 |
| Net client recovery | $75,000 |
This simplified illustration assumes fees are calculated on the gross recovery and all listed deductions are permitted.
If an approved medical lien decreases, the client’s recovery automatically increases when the system recalculates. That eliminates the need to update multiple document fields manually.
3. Automate Date-Based Prorations
Real estate settlements frequently include expenses shared between buyers and sellers. Property taxes, rental income, association assessments, and certain utilities may require prorated adjustments.
Consider an illustrative annual property tax of $6,000.
Using a 365-day year:
Daily tax = $6,000 ÷ 365 = $16.44
If the seller is responsible for 120 days:
Seller’s allocation = $6,000 × 120 ÷ 365 = $1,972.60
The system should recalculate the allocation whenever the closing date changes.
Proration conventions differ by contract and jurisdiction, so software must accommodate actual calendar days, contractual responsibility dates, and applicable local rules.
The Internal Revenue Service also provides guidance on real estate tax allocations between buyers and sellers for federal tax purposes.
4. Select Software That Supports Your Workflow
Settlement automation can operate through specialized software or a properly structured spreadsheet. Legal case-management solutions such as Filevine and LEAP offer settlement-related capabilities, while AI-assisted document platforms may extract financial details from uploaded records.
Real estate closing systems can manage prorations, recording charges, and buyer-seller accounting. For smaller operations, Microsoft Excel or Google Sheets can provide an economical starting point.
Create separate worksheets for transaction inputs, deductions, calculation rules, and statement summaries. Functions such as SUM, IF, and XLOOKUP can automate arithmetic and retrieve approved rates. Protect formula cells to prevent accidental modification.
Spreadsheets remain useful, but they require additional controls for permissions, version history, and reconciliation.
5. Generate Statements Automatically
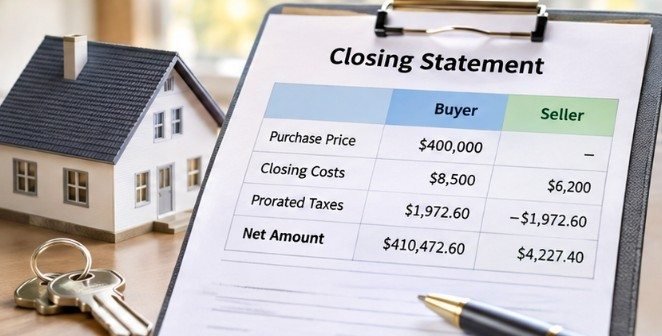
After calculations are validated, transfer the approved figures into standardized settlement documents. Document automation can populate recipient names, transaction details, deductions, and final payment amounts.
A legal settlement workflow might generate a client disbursement statement alongside an internal payment authorization. Real estate software may create ALTA settlement forms and supporting closing documents.
Automated document creation eliminates repeated transcription, but reviewers must still verify that every amount appears in the correct location.
6. Validate Totals Before Releasing Funds
Financial reconciliation should be mandatory rather than optional. A legal settlement should satisfy this control:
Gross Settlement = Total Approved Disbursements + Remaining Undisbursed Balance
For real estate closings, independently reconcile buyer and seller figures, loan proceeds, deposits, charges, and escrow movements.
The Consumer Financial Protection Bureau recommends reviewing closing costs, estimated payments, and cash-to-close information against previous loan disclosures.
Many covered mortgage transactions also require borrowers to receive a Closing Disclosure at least three business days before consummation, subject to applicable exceptions.
Add Controls That Catch Errors Before Clients Notice
Automation is only as dependable as the underlying information. A missing medical lien, outdated property tax rate, or duplicated expense can produce a mathematically correct but financially inaccurate statement.
Effective safeguards include automated duplicate detection, required-document checks, approval permissions, and audit logs.
Configure alerts when settlement totals fail to balance or when expenses exceed authorized amounts. Use a two-person review for disbursement approvals, particularly when client trust accounts are involved.
For firms seeking greater financial visibility, connecting law firm accounting to Power BI can support reporting on reconciliation exceptions, settlement activity, and financial performance.
A useful test is to change one approved input and confirm that every dependent calculation updates correctly without modifying unrelated transactions.
Where Artificial Intelligence Helps—and Where It Doesn’t

AI-assisted tools can identify figures in invoices, extract payment information, and draft settlement summaries. Their value is primarily in reducing document processing and administrative work.
However, extracted numbers may be incomplete or incorrectly classified. AI-generated calculations should therefore be verified using deterministic formulas and original records. Sensitive client information also requires appropriate access controls and confidentiality protections.
The Cornell Legal Information Institute publishes federal disclosure regulations that illustrate why mortgage closing workflows must account for legally defined timing and documentation requirements.
No automation tool should independently authorize final trust-account disbursements without appropriate human oversight.
Make Settlement Automation Part of a Better Client Experience
An accurate statement is only one part of a successful settlement process. Clients also need clear explanations, timely updates, and confidence that deductions have been reviewed.
Automated notifications can inform clients when settlement documentation is ready or when an authorized payment has been processed.
After the matter closes, firms can incorporate past-client reactivation automation into their broader relationship-management strategy, subject to confidentiality and applicable professional conduct rules.
Combining reliable calculations with thoughtful communication helps reduce confusion and unnecessary follow-up requests.
Frequently Asked Questions
1. Can Excel automate settlement statement calculations?
Yes. Excel can calculate attorney fees, deductions, prorations, and final balances using formulas. However, complex workflows benefit from stronger access controls, integrations, and approval tracking.
2. What is the best software for settlement calculations?
The best choice depends on transaction type. Legal firms may prefer case-management platforms, while real estate professionals typically need closing software with jurisdiction-specific fee and proration capabilities.
3. How do automated settlement systems prevent errors?
They use standardized formulas, centralized records, validation rules, reconciliation checks, and approval workflows. Human review remains essential for confirming source data and authorizing payments.
4. Can AI prepare legally compliant settlement statements?
AI can assist with extracting information and drafting documents, but compliance depends on verified calculations, applicable laws, accurate records, and qualified professional oversight.
The Final Calculation Should Never Be a Guess
The strongest settlement automation systems do more than save administrative time. They make financial decisions easier to verify, explain, and defend.
Whether processing a personal injury recovery or coordinating a property closing, the underlying principle remains the same: every amount should have a documented source, a consistent calculation method, and an authorized reviewer.
Start with one frequently used settlement template. Automate its calculations, test unusual scenarios, and compare the results against independently verified figures before expanding the workflow.
A faster statement is useful. A statement that clients and professionals can confidently reconcile is far more valuable.