A law firm can verify a client’s identity and still overlook the person secretly controlling the transaction. That distinction makes financial crime prevention far more complicated than collecting passports and checking names.
An automated anti money laundering checks law firm solution connects identity verification, beneficial ownership research, sanctions screening, and transaction risk assessment within a structured digital workflow.
For American legal practices, the challenge extends beyond efficiency. Attorneys must recognize suspicious activities without compromising confidentiality, professional independence, or client relationships. The right technology helps identify warning signs early, documents decisions, and allows lawyers to concentrate on risks that genuinely require professional judgment.
How Automated AML Screening Works Inside a Legal Practice
Modern compliance platforms combine several screening processes rather than treating identity verification as a standalone administrative task.
Digital Identity and Corporate Ownership Verification
Client onboarding begins by establishing who the firm represents.
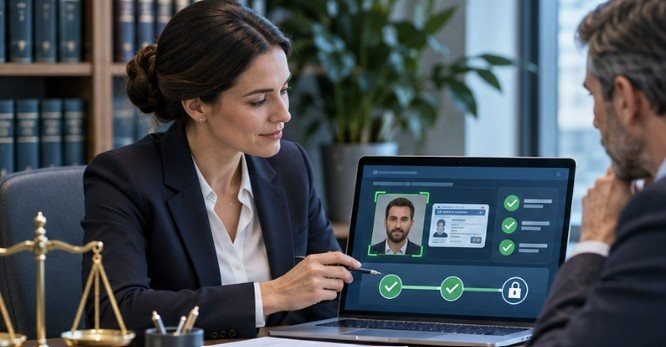
For individuals, software may examine government-issued identification, compare photographs with live biometric captures, and flag inconsistent personal information.
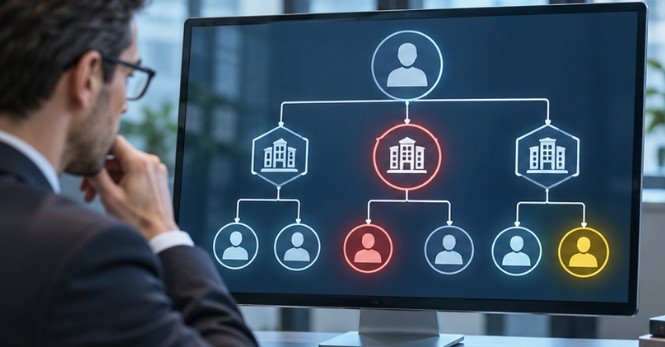
For businesses, know-your-business verification examines registration records, corporate relationships, and individuals exercising ownership or control.
Consider an LLC purchasing commercial property through several holding companies. Automated ownership mapping may expose relationships that ordinary document collection misses.
Importantly, identifying beneficial owners for risk assessment differs from filing beneficial ownership information with FinCEN. An August 2026 final rule maintained the exemption for domestic companies from federal Corporate Transparency Act BOI reporting.
Sanctions, PEP, and Negative News Screening
Automated systems compare client information against sanctions databases, politically exposed persons lists, and adverse media records.
A politically exposed person is someone holding, or closely connected to someone holding, a prominent public position. Such status indicates potential exposure to corruption risk, not criminal wrongdoing.
The Office of Foreign Assets Control provides guidance for evaluating potential sanctions matches. A shared name alone does not establish a violation. Attorneys must assess identifiers, relationships, ownership, and relevant restrictions before making decisions.
Continuous Monitoring and Intelligent Risk Alerts
A client might pass initial screening but develop new risk indicators months later. Monitoring systems can detect updated sanctions listings, changes in corporate ownership, and newly published adverse information.
Risk scoring helps prioritize these findings according to factors such as transaction complexity, geographic exposure, client structure, and source-of-funds concerns.
The objective is not to investigate every client equally. It is to direct attention toward matters involving meaningful financial crime exposure.
Connecting AML Checks With Existing Law Firm Software
Standalone compliance dashboards often create additional administrative work. Integrated systems connect screening results with client intake, matter management, and document storage.
Solutions such as azakaw, Legl, Verify 365, and LSEG World-Check One offer different combinations of identity verification, watchlist screening, ownership research, and monitoring.
Aderant’s integration with First AML illustrates how compliance tasks can become part of legal practice management. Hoowla similarly combines matter administration with due diligence functionality.
Firms exploring how to automate law firm client onboarding should ensure that unresolved AML alerts prevent premature matter approval.
Well-designed integrations also preserve timestamps, reviewer decisions, supporting documents, and screening outcomes.
A Practical Five-Step AML Implementation Process
Successful automation requires a defined workflow before purchasing software.
Step 1: Classify Matters by Exposure
Separate routine advisory matters from transactions involving substantial funds, complex corporate ownership, or unfamiliar international counterparties.
The Financial Action Task Force recommends tailoring due diligence to the risks associated with legal services, clients, and transactions.
Step 2: Establish Verification Requirements
Determine which identity documents, corporate records, and ownership details each client category requires. Avoid requesting sensitive information without a legitimate purpose.
Step 3: Configure Screening and Escalation
Set screening frequency, risk thresholds, and procedures for suspicious findings. Assign qualified reviewers to investigate possible sanctions matches and unusual financial arrangements.
Step 4: Connect Compliance With Matter Management
Use APIs or webhooks in legal software to synchronize verification outcomes, trigger internal notifications, and update onboarding status. Never allow a technical integration to override a required attorney review.
Step 5: Test Performance Regularly
Review false positives, unresolved alerts, incomplete records, and delayed investigations.
Document adjustments and provide staff training whenever screening procedures change.
Choosing Software Without Paying for Unnecessary Features
An automated anti money laundering checks law firm platform should match the firm’s actual practice areas and risk exposure.
A small estate-planning practice might prioritize straightforward identity verification and secure records. A corporate transactions firm may need sophisticated ownership mapping, international sanctions coverage, and continuous monitoring.
Before signing a contract, request demonstrations using realistic scenarios rather than vendor-prepared examples.
Evaluate whether the platform can distinguish similar names, identify indirect ownership relationships, explain risk ratings, and export complete review histories.
Also examine encryption, access controls, retention settings, data residency, and vendor subcontractors. Confidential client information should never enter an external screening system without appropriate safeguards.
What Automation Cannot Replace
Automated checks are not legal conclusions. False positives can delay legitimate clients, while incomplete databases may overlook concealed relationships. Biometric verification can confirm identity without establishing the legitimacy of a transaction.
Confidentiality obligations also require careful consideration before transmitting privileged or sensitive information to outside providers.
Additionally, federal requirements continue evolving. FinCEN’s residential real estate guidance confirms that a March 19, 2026, court decision vacated the federal residential real estate reporting rule. Reporting obligations under that rule remain suspended while the order is in force.
Firms must distinguish current legal obligations from voluntary risk-management practices, while checking relevant state requirements.
Frequently Asked Questions
1. Are automated AML checks mandatory for every American law firm?
No. Requirements depend on applicable laws, activities, and professional obligations. However, risk-based client screening can help firms identify suspicious circumstances and support ethical compliance.
2. How frequently should law firms screen existing clients?
Frequency should reflect client and matter risks. Higher-risk relationships may warrant continuous screening, while lower-risk matters can follow periodic or event-triggered reviews.
3. Can AML software verify the source of client funds?
Software can collect financial documentation, identify inconsistencies, and flag unusual transactions. Establishing whether funds are legitimate often requires additional evidence and professional judgment.
4. What is the biggest advantage of automated AML checks?
Consistent screening is a major benefit. Automation reduces repetitive work, records compliance decisions, and helps legal professionals investigate meaningful risks earlier.
Building a More Defensible Compliance Process
The greatest danger in client due diligence is assuming that verified identity automatically means verified legitimacy.
Effective automation challenges that assumption. It combines reliable screening data, carefully designed workflows, documented decisions, and meaningful human oversight.
For firms evaluating an automated anti money laundering checks law firm system, the strongest starting point is a review of existing client intake procedures rather than a software demonstration.
Identify where information disappears, alerts remain unresolved, or approvals lack documentation. Then introduce technology that closes those gaps.
The goal is not simply faster onboarding. It is knowing whom the firm represents, understanding the associated risks, and recognizing when further questions are necessary.