
A law firm can generate thousands of dollars in billable work while struggling to explain where its profits actually went. Unpaid invoices, unbilled hours, and disconnected accounting records often hide the answer.
Understanding how to connect law firm accounting to Power BI helps attorneys and finance teams turn scattered financial information into interactive reports. Instead of manually combining spreadsheets, firms can monitor revenue, expenses, cash flow, and matter profitability from a centralized dashboard.
The process involves choosing a suitable connection, preparing financial records, building reporting models, and protecting confidential client information.
Choose the Right Accounting Connection Method
The best integration depends on the firm’s existing software, technical resources, and reporting requirements.
Native Connectors for Faster Implementation
Some legal practice management platforms provide dedicated Power BI integrations. LEAP Legal Software, for example, advertises a Microsoft-certified Power BI connector designed for legal practice reporting.
A supported connector can reduce custom development because it already understands certain source structures. Before selecting one, confirm which financial tables are available, whether additional licensing applies, and whether the connector supports the firm’s installed version.
REST APIs and OData for Flexible Reporting
Cloud accounting platforms may provide application programming interfaces that allow authorized applications to retrieve financial information.
Power Query can consume supported OData feeds and web endpoints. More complex REST APIs may require custom queries, pagination handling, or an intermediate database.
This approach provides flexibility but demands careful management of authentication, API limits, and changing data structures.
SQL Databases and Scheduled File Exports
Older accounting systems may lack modern integration features. When supported, Power BI can retrieve information from a read-only SQL reporting database. Alternatively, firms can import consistently structured CSV or Excel exports.
Scheduled exports are often sufficient for weekly profitability reporting, although they cannot provide genuinely live financial information.
How to Connect Law Firm Accounting to Power BI Step by Step
A successful implementation starts with accounting definitions rather than dashboard colors.
Step 1: Identify the Financial Questions
Begin by deciding what partners and administrators need to understand. Common measurements include utilization, realization, work in progress (WIP), lock-up, accounts receivable, collection rates, and matter profitability.
Utilization measures billable time against available working time. Realization compares the value ultimately billed with the standard value of work performed, although firms may use different definitions.
Lock-up generally reflects revenue tied up in unbilled work and unpaid invoices. Document each metric’s formula before building reports so departments interpret results consistently.
Step 2: Gather and Standardize Financial Data
Open Power BI Desktop and select Home > Get Data. Choose the appropriate connector, authenticate through an approved account, and load relevant source tables.
Typical datasets include general ledger transactions, operating expenses, invoices, payments, time entries, clients, matters, and timekeepers. Trust account information requires separate handling.
Use Power Query to standardize dates, normalize matter identifiers, remove unintended duplicates, and validate transaction amounts. Preserve original transaction IDs and source records so discrepancies remain traceable.
Step 3: Design a Reliable Data Model
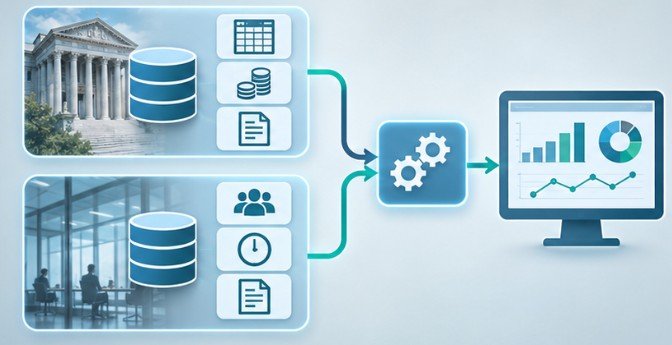
Rather than joining every spreadsheet into one enormous table, create a star schema. This structure separates transaction records into fact tables and descriptive information into dimension tables.
For example, invoice transactions, time entries, and expenses can connect to shared matter, client, employee, and calendar dimensions. Use clearly defined relationships and avoid ambiguous many-to-many joins.
Power BI’s Data Analysis Expressions (DAX) language then calculates measures such as outstanding receivables and collected revenue. A clean model prevents one invoice from accidentally appearing multiple times after joins.
Step 4: Create Dashboards That Answer Business Questions
Build separate reporting views for firm leadership, accounting staff, and practice managers. Leadership might monitor operating profit, revenue trends, and collection performance.
Practice managers may need matter budgets, staffing costs, unbilled time, and realization rates. Include date filters, department comparisons, and matter-level drilldowns where access permissions allow. Start with a small number of reliable measures before introducing advanced forecasting.
Step 5: Publish Reports and Configure Refreshes
After validating calculations, publish the report to an authorized Power BI workspace. Configure data source credentials and, where required, an on-premises data gateway.
Microsoft supports up to eight scheduled daily refreshes on shared capacity and up to 48 on eligible Premium or Fabric configurations, subject to applicable limits.
A daily refresh may be sufficient for smaller firms. More frequent refreshes are useful only when source systems update often enough to justify them. Monitor failures and display the most recent successful refresh timestamp.
Protect Client Confidentiality and Trust Accounts
Financial reporting in American law firms carries responsibilities beyond ordinary business analytics.
The American Bar Association’s Model Rule 1.15 addresses safeguarding client property and maintaining separate client funds.
Trust and IOLTA balances must therefore remain distinguishable from operating revenue.
Power BI may help identify unusual balances or reconciliation discrepancies, but it should never replace required trust-account records or reconciliations.
The ABA’s Rule 1.6 also establishes confidentiality responsibilities concerning client information. Apply row-level security so authorized users see only permitted records.
Crucially, Power BI row-level security does not restrict workspace Administrators, Members, or Contributors in the same way it restricts Viewers.
The National Institute of Standards and Technology recommends least-privilege access, meaning users receive only the permissions necessary for their responsibilities.
Combine restricted permissions with multifactor authentication, controlled exports, and periodic access reviews. State-specific professional conduct requirements must also be checked.
Measure Profitability Without Misleading the Partners
Consider a hypothetical U.S. law firm evaluating a commercial litigation matter.
The firm billed $80,000, collected $68,000, and attributed $42,000 in direct labor and case expenses.
Its simplified collected-revenue contribution would be:
$68,000 − $42,000 = $26,000
That represents approximately 38.2% of collected revenue.
However, it is not necessarily net profit because shared overhead, taxes, and additional allocated expenses may remain excluded.
The dashboard should distinguish billed revenue, collected revenue, direct costs, and allocated overhead rather than combining them into a misleading profit figure. This distinction can change how partners evaluate staffing, pricing, and matter budgets.
Common Integration Problems Worth Checking
A successful data connection does not guarantee trustworthy financial reports. Missing invoices may indicate insufficient API permissions or an incomplete extraction window. Incorrect totals can result from duplicate joins, inconsistent accounting periods, or mismatched matter identifiers.
Refresh failures may involve expired credentials, unavailable gateways, or unsupported transformations. Compare dashboard totals against approved source reports before rollout.
Also verify that operating revenue excludes client trust deposits, refunds are handled consistently, and closed matters retain their historical reporting information.
A monthly reconciliation between the reporting model and accounting system can reveal problems before they affect management decisions.
Frequently Asked Questions
1. Can Power BI connect directly to legal accounting software?
Yes, when the software supports a compatible connector, database connection, or data feed. Otherwise, an API integration or scheduled file export may be necessary.
2. Does Power BI replace legal accounting software?
No. Power BI analyzes and presents financial information. The accounting platform remains responsible for recording transactions and maintaining the authoritative books.
3. How often should law firm accounting dashboards refresh?
Daily updates generally work for routine management reporting. Firms needing faster operational visibility can refresh more frequently when their licenses, data sources, and infrastructure support it.
4. Is Power BI suitable for confidential legal financial records?
Yes, with appropriate access controls, secure connections, restricted sharing, and compliance review. Firms must also follow applicable state confidentiality and trust-account requirements.
Build Financial Clarity Before Complexity
Learning how to connect law firm accounting to Power BI is less about creating sophisticated charts and more about establishing dependable financial visibility.
A dashboard becomes valuable when its figures match the accounting records, its calculations have consistent definitions, and its users can make decisions without questioning the data.
Start with one dependable financial report, validate it against the ledger, and expand gradually into profitability, collections, and workload analytics.
For U.S. law firms, financial intelligence must always coexist with client confidentiality and trust-account safeguards. Especially for law firm past client reactivation automation is needed.
The most useful dashboard is not the one displaying the most numbers. It is the one partners can trust when making consequential decisions.

One thought on “A Practical Guide on How to Connect Law Firm Accounting to Power BI”